The Pilot's Financial Walkaround
If you're a pilot, you've been trained to manage risk with a level of discipline most people never develop. Pre-flight walkaround. Checklists. Redundant systems. Contingency planning for contingencies.
And then you land, drive home, and leave your financial life completely unplanned.
The same rigor that keeps a 90-ton aircraft in the air rarely makes it into a pilot's personal balance sheet. That's the problem.
One Medical Away from Zero
High airline income feels permanent until the day it isn't.
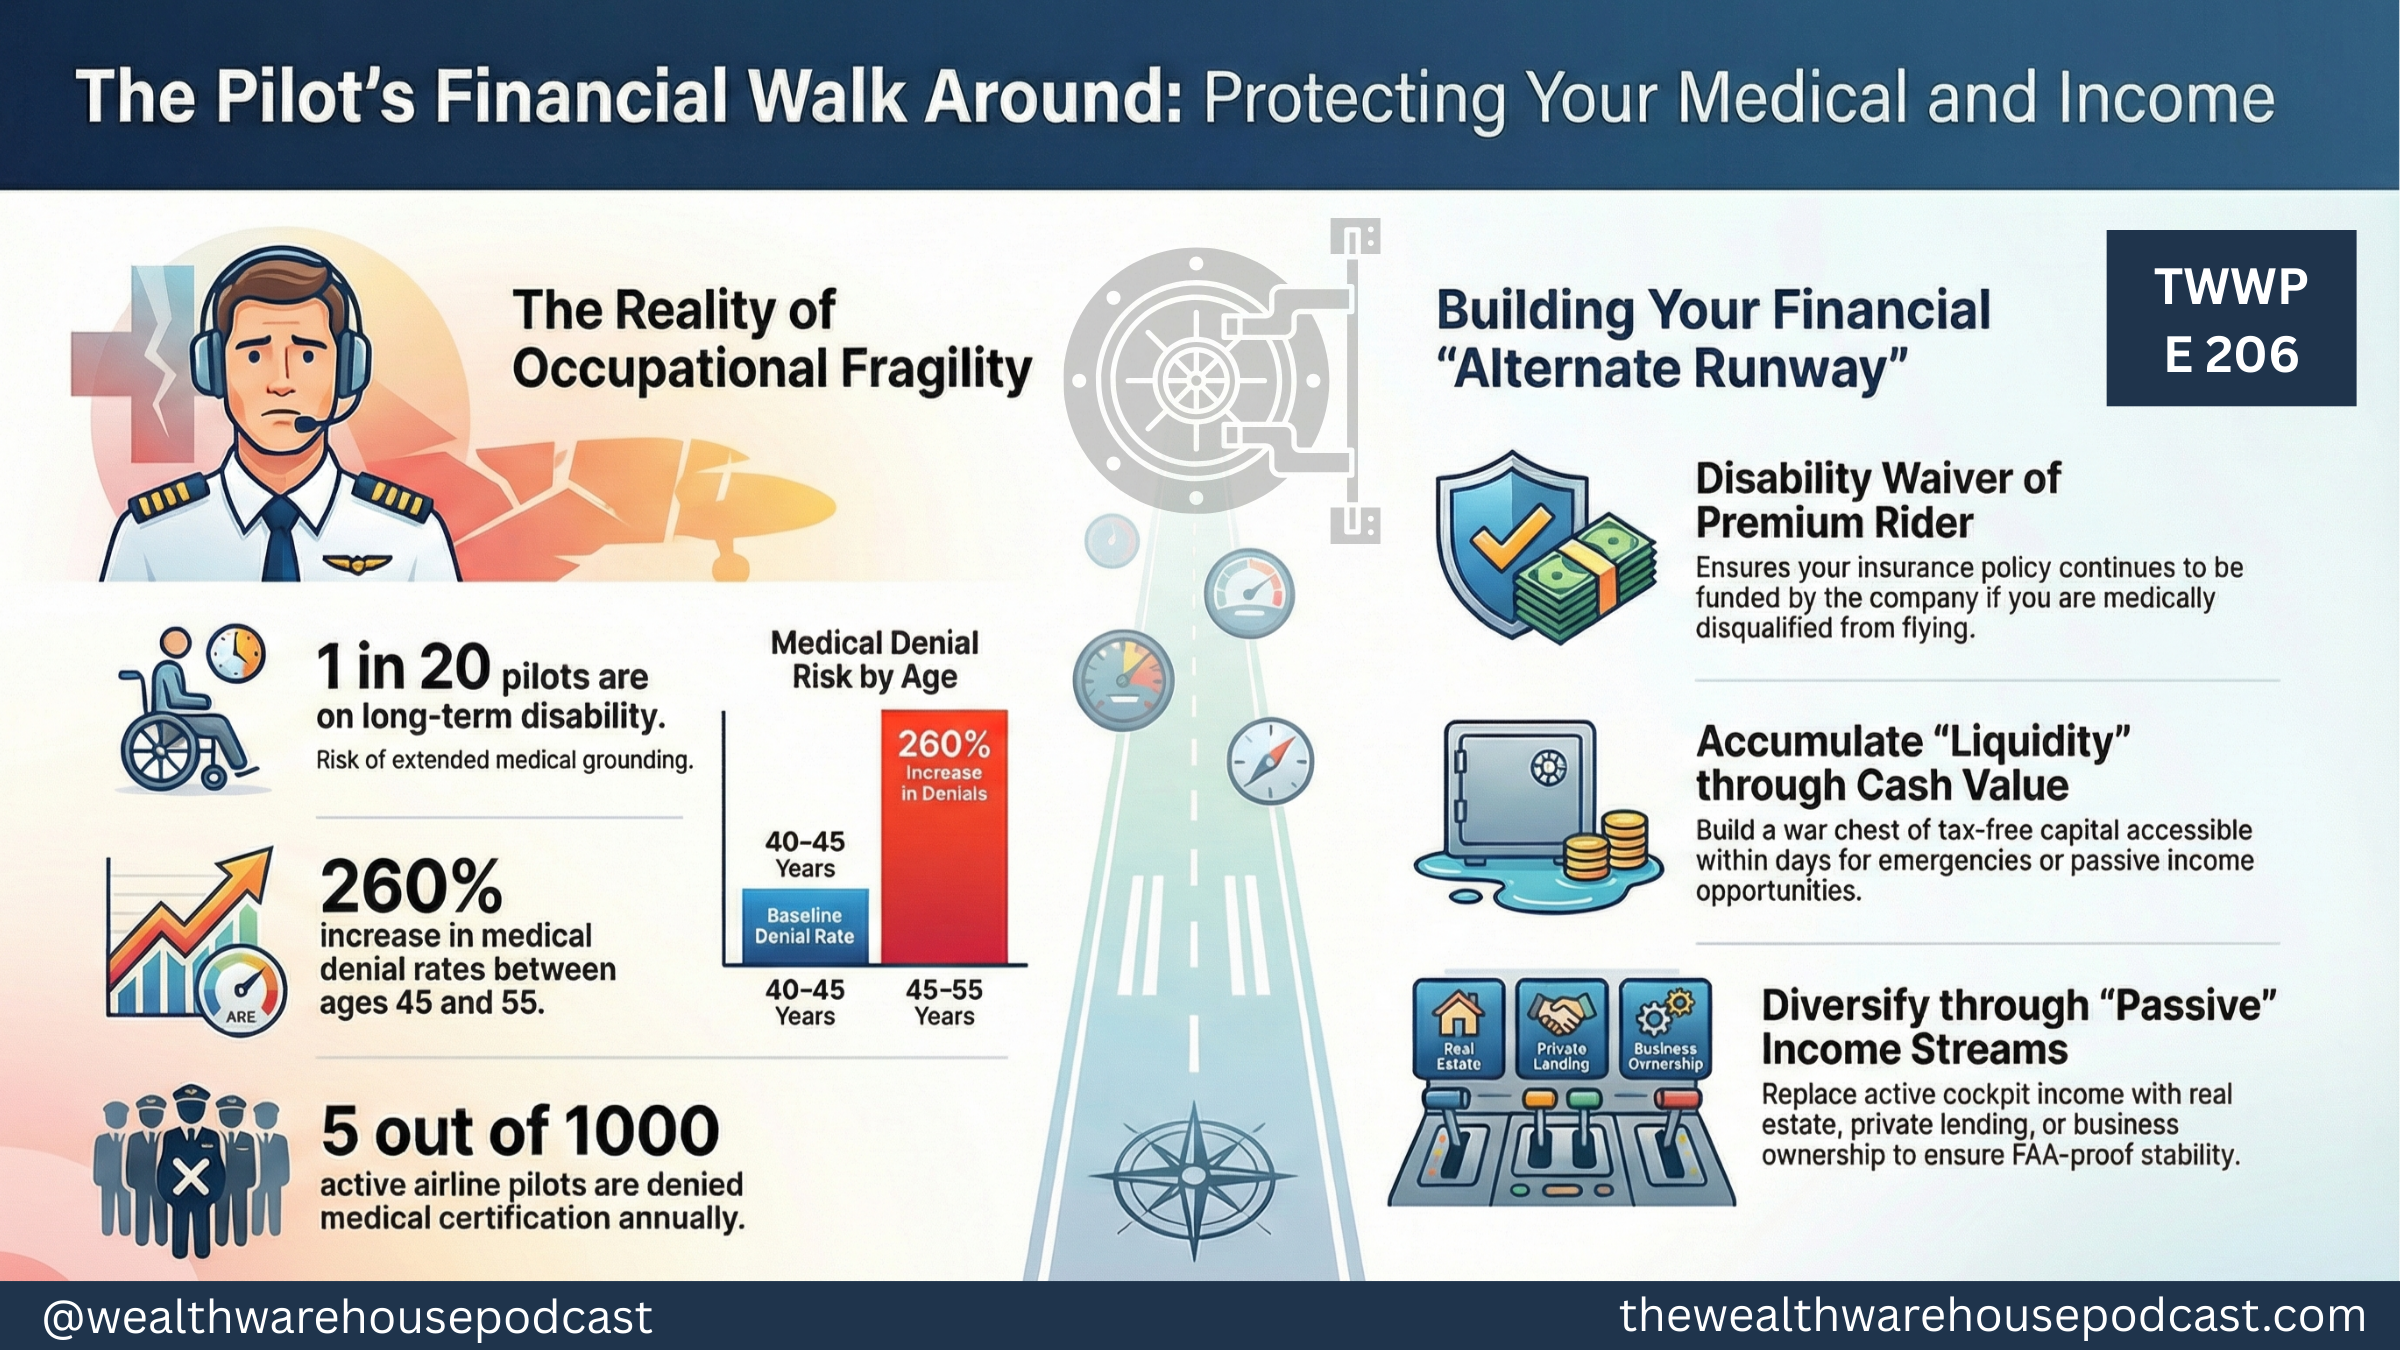
Approximately five out of every 1,000 active airline pilots lose medical certification each year. One in twenty are on long-term disability at any given time. These aren't edge cases — they're statistical certainties distributed across a profession.
A $300,000 salary that disappears overnight because of a cardiac event, a failed vision test, or two bad knees isn't a safety net. It's a trap with a long fuse.
Most pilots' wealth is concentrated in two places: the equity in their home and the balance in their 401(k). Neither is accessible without significant friction, cost, or penalty when an emergency hits.
What a Financial Walkaround Actually Looks Like
You wouldn't take off without checking the aircraft. Apply the same standard to your finances.
The first question: if your income stopped tomorrow, what happens in month two? Month six? If the answer involves selling assets, drawing penalties, or calling family members — you don't have a plan. You have a delay.
The second question: where is your capital actually working? Money sitting in a savings account is losing purchasing power. Money locked in a 401(k) is inaccessible. Home equity doesn't pay bills without a loan application.
Capital needs to be liquid, growing, and under your control simultaneously. That's a high bar. Most financial products don't meet it.
The Waiver of Premium Rider
Here's one specific thing worth knowing.
A properly structured whole life policy with a waiver of premium rider will continue funding itself — the insurance company pays your premiums — if you become disabled and can't work.
Your bank will never do that. If your income stops, your mortgage doesn't pause. Your car payment doesn't pause. But a policy with this rider keeps building cash value even when your paycheck disappears.
It's the financial equivalent of an autopilot that actually works when you need to step away from the controls.
Don't Let a GoFundMe Be the Plan
High-income earners die underinsured and under-prepared more often than anyone wants to acknowledge. The income felt permanent. The lifestyle expanded to match it. The backup systems never got built.
A pilot who manages risk at 35,000 feet should be able to manage it at sea level too.
Do the walkaround. Find the gaps before they find you.
Photo by Unsplash
Ready to build your wealth warehouse?
Book a free strategy call with David & Paul and discover how IBC can work for you.

